ZIGsengBAG
Milestone-Based Fundraising and Long-Term Ownership Structure
Executive Summary
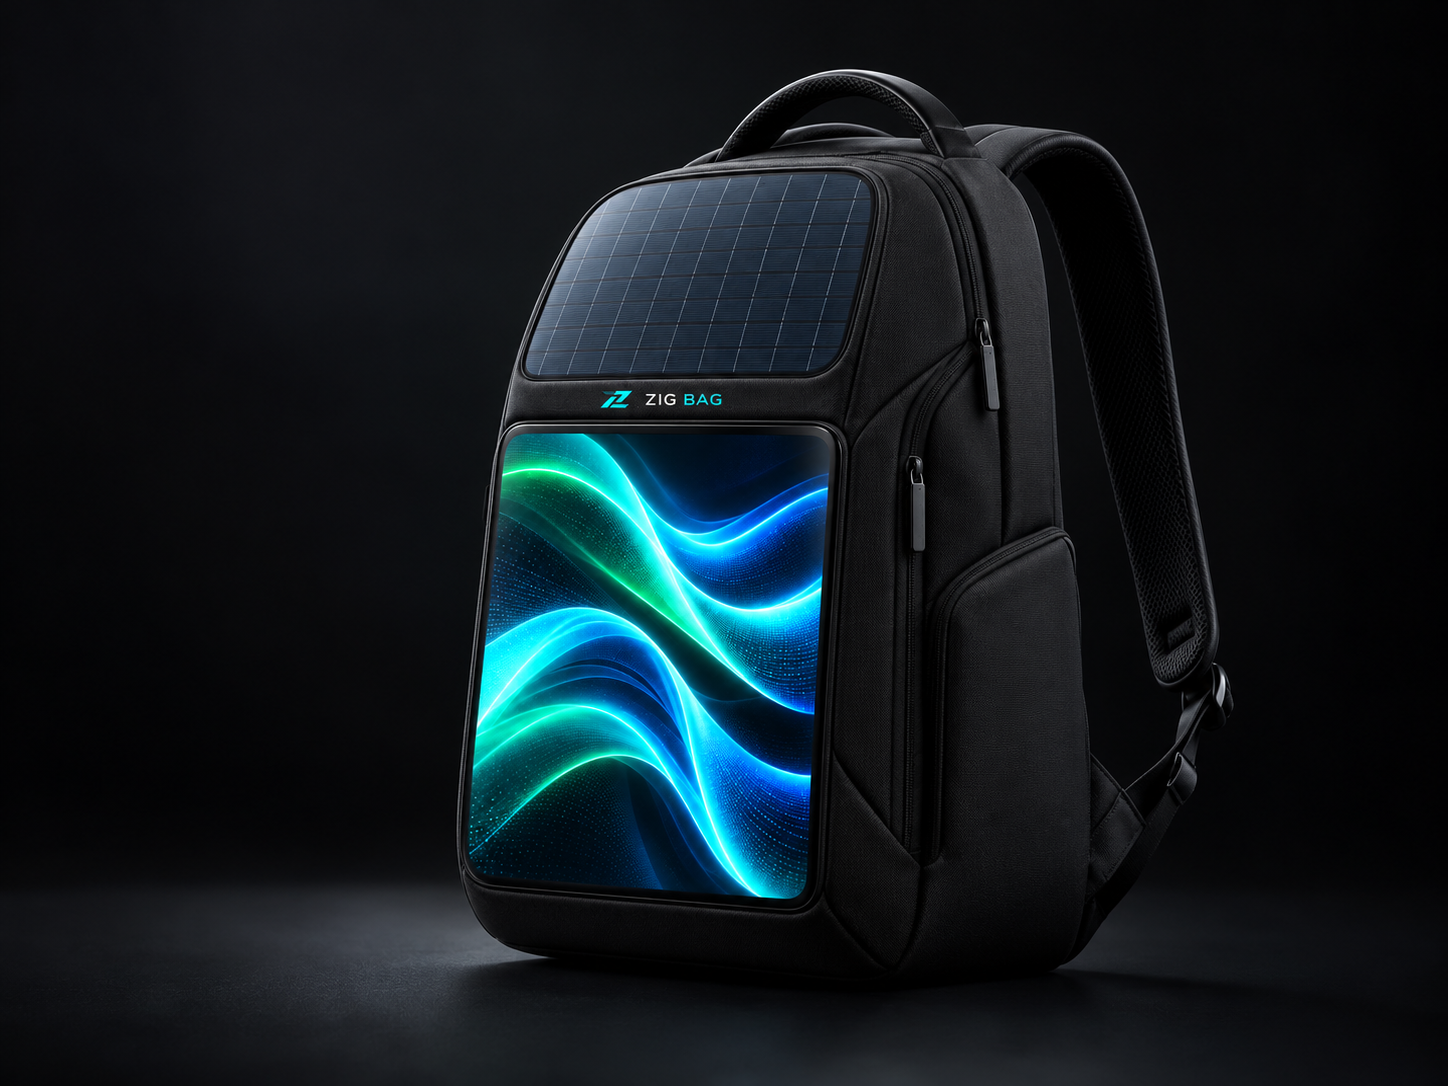
Zigseng aims to build an international, technology-driven bag brand that combines everyday practicality with a digital display, a mobile app, and smart features introduced progressively.
In its first investment round, the company plans to raise a total of $308,700 USD in development and growth capital, a 10% equity stake in exchange.
The investment in four tranches would be made. The three tranches following the initial funding would be released based on verified customer numbers and predefined business conditions. The structure is intended to align the provision of capital with the company’s market progress.
Under the long-term target ownership structure, the founder would retain a 51% stake the first-round investor would acquire 10%, and a total of 39% would be available to future investors in subsequent rounds.
The Business and Product Concept
Zigseng is built around the development of a private-label product line and related digital services.
The core elements of the product concept are:
- Bags equipped with a digital display.
- Visual content managed through a mobile application.
- Features that enable a distinctive look and personalization features.
- Product versions designed for both consumer and business use.
Potential future development areas include child-safety features, location tracking, SOS alerts, NFC solutions, and power and charging features. Their introduction is subject to technical assessment and product testing and a separate business decision.
The goal of brand-building is to ensure that Zigseng products have a consistent appearance, consistent quality and a distinctive digital user experience.
Target Markets and Revenue Model
The proposed business model is based on three sales channels .
| Sales Channel | Target Group | Proposed Revenue Source |
|---|---|---|
| Direct-to-Consumer Sales | Individual Customers | Products sold through the company’s own website |
| Commercial Partner Network | Resellers and Distributors | Sales through Partners |
| Business Use | Brands, Event Organizers, and Promotional Partners | Corporate Orders and Custom Partnerships |
Using the displays for advertising may create additional business opportunities. Related service or rental revenues require separate validationand therefore should not be treated in the initial business plan as guaranteed revenue .
Key Terms of the First Investment Round
| Parameter | Proposed Term |
|---|---|
| Total Investment Amount | $308,700 USD |
| Equity Stake Available | 10% upon payment of the full amount |
| Form of Financing | Development and growth capital invested in the company |
| Disbursement | Four tranches of $77,200 USD each each |
| Implied Pre-Money Valuation | $2,777,800 USD |
| Implied Post-Money Valuation | $3,086,500 USD |
| Use of Capital | Product development, digital systems, inventory, market entry, and operations |
| Potential Source of Investor Returns | Appreciation of the equity stake, its future sale, or distributions under the dividend policy |
The stated valuation follows from the proposed terms of the first investment round; it is not an independent company valuation. The structure does not include a guaranteed return or a mandatory buyback .
Funding Schedule
| Stage | Drawdown Milestone | Amount to Be Disbursed | Cumulative Investment |
|---|---|---|---|
| I. Launch | Execution of definitive agreements and fulfillment of launch conditions | $77,200 USD | $77,200 USD |
| II. Market Validation | 5,000 unique paying customers reached | $77,200 USD | $154,400 USD |
| III. Growth | 10,000 unique paying customers reached | $77,200 USD | $231,500 USD |
| IV. Expansion | 15,000 unique paying customers reached | $77,200 USD | $308,700 USD |
The customer counts represent cumulative milestones rather than additional customers to be acquired separately in each stage.
Equity ownership would be linked to the capital actually paid in The equity allocation mechanism for the tranches must be structured so that, upon completion of the full investment, the investor obtains exactly a 10% equity stake .
The definitive agreement should specify in advance:
- The milestones’ completion deadlines .
- The documents required to verify achievement.
- The investor’s verification deadline.
- The deadline for disbursement after verified achievement .
- How delays, failure to meet milestones and any changes to the business plan will be handled.
Customer Count and Performance Measurement
The milestones are based on the actual number of acquired, unique paying customers .
Under the proposed definition, a paying customer is a buyer with at least one paid, fulfilled, and non-refunded purchase. Repeat purchases by the same customer do not increase the customer count .
Verification would involve cross-checking order data, invoices, payments, and refunds.
Accounting for reseller and corporate sales must be regulated separately: a large partner order does not, by itself, equal the acquisition of the same number of individual end users.
The following should also be monitored regularly, alongside customer count:
| Metric | Business Significance |
|---|---|
| Net Revenue | Actual sales volume |
| Contribution Margin per Product | Product Economics |
| Customer Acquisition Cost | Ability to Finance Growth |
| Return and Warranty Claim Rate | Product Quality and Customer Satisfaction |
| Inventory and Inventory Turnover | Capital Tied Up in Inventory |
| Cash Balance and Funding Requirements | Business Continuity |
Pricing and Profitability Target
The initial business model aims to achieve a net selling price equal to four times the purchase price .
The comparison should be made on a like-for-like net basis The fourfold price multiple does not mean fourfold profit: the difference between selling price and purchase price must cover, among other things, logistics, marketing, sales, warranty, and operating expenses.
Different channels may have different margins . The economics of direct-to-consumer and reseller sales should therefore be presented separately.
To draw down the second and subsequent tranches, it must be demonstrated—alongside customer numbers—that the agreed pricing model has been achieved, for the period and using the calculation method specified in the definitive agreement.
Use of Raised Capital
| Area | Proposed Use |
|---|---|
| Product Development | Prototypes, technical solutions, product variants, and testing |
| Software Development | Mobile app, content management, and related digital infrastructure |
| Production Preparation | Supplier cooperation, sample production, and quality assurance |
| Product Compliance | Required testing and documentation |
| Inventory Financing | Initial inventory, reorders, and financing of the delivery cycle |
| Market Entry | Brand building, online sales, campaigns, and partner network |
| Operational Support | Customer service, logistics coordination, and financial administration |
The detailed budget should be approved before the investment decision, on a stage-by-stage basis .
The financial plan must separately demonstrate that the initial $77,200 USD and funds reinvested from sales may be sufficient to reach the first 5,000 customers . If additional working capital is required, its source must be addressed in advance in the funding plan.
Long-Term Target Ownership Structure
Target structure after the proposed investment rounds are completed:
| Ownership Group | Target Stake |
|---|---|
| Founder | 51% |
| First-Round Investor or Investor Group | 10% |
| Future Investors in Total | 39% |
| Total | 100% |
The founder’s objective is to retain majority ownership and ensure continuity of long-term strategic control.
The 39% planned for future investors may be raised across several successive rounds. This is a future target structure, not equity already allocated or automatically reserved.
The precise mechanism for preserving the founder’s 51% and the first-round investor’s 10% in future fundraising must be agreed in advance. These percentages do not remain in place automatically .
The definitive documentation must clearly specify how each round affects existing owners, and under what conditions the target structure can be maintained.
Subsequent Investment Rounds and Valuation
The company aims for investors entering after the first round to acquire stakes at a higher company valuation .
The higher valuation may be supported by documented business results achieved in the meantime:
- Growing paying-customer base and revenue.
- Demonstrated, sustainable product contribution margin .
- Operational and cost-effective sales channels .
- Reliable manufacturing and delivery operations.
- A more advanced product portfolio and digital system.
- International partnerships and fulfilled orders.
The first-round investment is associated with an earlier business stage and greater uncertainty . The planned higher price per unit of equity in later rounds must be supported by demonstrated progress .
An increase in future valuation is not guaranteed; it will always depend on the company’s current results and negotiations with investors.
Each subsequent round must specify whether the transaction provides new capital to the company, involves purchasing an existing owner’s stake, or combines both.
Corporate Governance and Investor Reporting
The investment partnership is based on regular reporting, the verifiable use of funds and clear decision-making accountability .
Proposed operating framework:
| Area | Proposed Practice |
|---|---|
| Business Reporting | Monthly management metrics and detailed quarterly report |
| Financial Planning | Annual budget and regularly updated cash-flow plan |
| Tracking Invested Capital | Reporting use by development and operating purpose |
| Material Decisions | Predefined owner approval process |
| Related-Party Transactions | Transparent terms and documented decision-making |
| New Fundraising | Prior disclosure of ownership impact and investment terms |
The investor rights, voting rules, and management authority will be governed by the definitive agreements.
Key Risks and Mitigation
| Risk Area | Proposed Mitigation Approach |
|---|---|
| Market Demand | Test sales, customer feedback, and gradual expansion |
| Pricing and Customer Acquisition | Measure contribution margins by channel and track campaign results |
| Manufacturing Quality | Inspect samples, document quality requirements, and perform acceptance testing |
| Software and Technology | Clarify usage rights, access permissions, and development responsibilities |
| Inventory and Liquidity | Scheduled purchasing and continuous cash-flow planning |
| Product Compliance | Ensure required testing and documentation before placing products on the market |
| Missed Milestones | Predefined review and funding procedure |
Milestone-based funding stages the investor’s capital exposure, while also ensuring that the continuity of funding required for operations is maintained.
Investor Returns and Potential Exit
Potential sources of investor returns:
- The Future sale of the equity stake to a new investor.
- A partial or full acquisition of the company by a strategic buyer .
- Distributions from profitable operations in accordance with the approved dividend policy .
- During the early growth stage, the company’s planned priority is development and reinvestment of profits .
The exit’s timing, value, and completion are not guaranteed. Tag-along, transfer, and other ownership terms must be addressed in the definitive documentation.
The Investment Process
Preliminary Discussions: review of investor objectives and key transaction terms.
Confidentiality and Information Sharing: presentation of the business plan, financial model, and product documentation.
Due Diligence: business, financial, technical, and legal review.
Agreement on Terms: valuation, milestones, equity acquisition, and investor rights.
Definitive Agreements: signing contracts and fulfilling launch conditions.
Initial Disbursement: provision of $77,200 USD.
Implementation and Monitoring: regular reporting, followed by drawdowns of further tranches based on achieved milestones.
Document Status: preliminary investment discussion material. The business objectives and ownership percentages presented are proposed terms . This document does not state an intention or readiness to pursue a stock exchange listing, and does not constitute a public securities offering or include a guaranteed return .
FURTHER FUNDRAISING PLAN – 39% EQUITY STAKE
Funding Strategy
After the first investment round, Zigseng plans to raise an additional total equity stake of 39% through four consecutive investment rounds .
Under the proposed pricing, in each new round the investment required to acquire each unit of equity doubles . In the first three additional rounds, 10% each, while 9% would be allocated to investors in the final round.
The price increase is a targeted offer term: its acceptability must be supported by the company’s business results and progress .
Proposed Pricing for the Additional 39%
| Investment Round | Equity Offered | Price per Equity Unit vs. First Round | Investment in EUR | Investment in USD |
|---|---|---|---|---|
| Round II | 10% | 2× | 545 777 EUR | 610 725 USD |
| Round III | 10% | 4× | 1 091 554 EUR | 1 221 449 USD |
| Round IV | 10% | 8× | 2 183 108 EUR | 2 442 897 USD |
| Round V | 9% | 16× | 3 929 595 EUR | 4 397 215 USD |
| Total Additional Fundraising | 39% | — | 7 750 034 EUR | 8 672 286 USD |
In the final round, the investor would acquire 9% at twice the unit price of the preceding round. As a result, the total investment would be 1.8 times the previous round’s amount .
The amounts are rounded to whole currency units and calculated from the original investment base using the previously established exchange rates. EUR and USD are alternative expressions of the same investment. .
Overall Funding Plan
| Investor Group | Proposed Final Stake | Investment in EUR | Investment in USD |
|---|---|---|---|
| First-Round Investor | 10% | 272 889 EUR | 305 362 USD |
| Second-Round Investors | 10% | 545 777 EUR | 610 725 USD |
| Third-Round Investors | 10% | 1 091 554 EUR | 1 221 449 USD |
| Fourth-Round Investors | 10% | 2 183 108 EUR | 2 442 897 USD |
| Fifth-Round Investors | 9% | 3 929 595 EUR | 4 397 215 USD |
| Investors in Total | 49% | 8 022 923 EUR | 8 977 648 USD |
| Founder | 51% | — | — |
The overall program therefore aims to raise approximately EUR 8.02 million / USD 8.98 million in capital, with a total target investor stake of 49% .
Proposed Business Terms for the Investment Rounds
It is advisable to link the opening of subsequent rounds to the company’s progress. The following terms are planning proposals; their numerical targets should be specified in the detailed business plan.
| Round | Proposed Milestone Supporting Higher Pricing | Primary Use of Capital |
|---|---|---|
| Round II | Completion of the first funding program, 15,000 verified paying customers and documented product contribution margin | Inventory expansion, sales, and customer service development |
| Round III | Sales operating in multiple markets, repeatable customer acquisition and reliable delivery | International expansion and partner network |
| Round IV | Significantly growing revenue, stable operations, and demonstrated corporate demand | Development of the product portfolio, technology, and corporate business |
| Round V | More predictable financial performance, broader market presence, and operations suitable for institutional investor due diligence | Larger-scale international growth |
Before launching the next round, an updated financial plan, capital-use budget, and investor valuation would be prepared.
Target Ownership Structure
Proposed ownership distribution after completion of the full program:
| Ownership Group | Final Target Stake |
|---|---|
| Founder | 51% |
| First Investment Round | 10% |
| Second Investment Round | 10% |
| Third Investment Round | 10% |
| Fourth Investment Round | 10% |
| Fifth Investment Round | 9% |
| Total | 100% |
The percentages in the table represent the target stakes after the full program. In successive capital increases, existing owners’ stakes may be diluted, so the allocation above does not occur automatically .
The definitive structure must separately establish how the founder’s 51% and each investor round’s target stake will be maintained while the invested capital goes to the company. Issuance amounts, ownership changes, and any adjustments for each round must be presented in a detailed capitalization table .
Investment Principle
Under the funding strategy, investors entering earlier can acquire stakes at a lower price per unit , while later investors would pay a higher price for the business progress demonstrated in the meantime .
The proposed pricing steps are 2×, 4×, 8×, and 16× compared with the first round. This is not a guaranteed increase in valuation or investor return: each round depends on results achieved, due diligence, and agreements with investors.
Document Status: preliminary funding and pricing plan. The definitive fundraising structure, ownership mechanism, and disbursement terms must be set out in separate agreements .